

Vendor Payment Automation Resources
Vendor Payment Automation Resources
Without vendor payment automation, every paper check your organization writes is a cost center. Printing, mailing, reconciling, re-issuing adds up fast, and that’s before you factor in the fraud exposure that comes with mailing check payments.
For AP, treasury, and finance teams, the pressure to modernize payment operations has never been higher. But moving away from checks is both a cost decision and an operational one. The how matters as much as the why.
This page is your starting point for understanding all things vendor payment automation, including the true cost of check-based payments, building the internal case for change, and executing a vendor migration to ACH without introducing new risk.
Building the business case for vendor payment automation
You already suspect checks are costing you more than they should, but you need data to back it up. You’re looking for a framework to quantify the cost of processing checks, model the savings from switching, and bring a credible ROI case to leadership. Start with our check cost breakdown to understand the full picture.
Already in motion
You’ve got buy-in. Now you need to execute. Migrating vendors to ACH sounds straightforward until you’re actually doing it — chasing down banking details, managing exceptions, and making sure you’re not trading check fraud risk for ACH fraud risk. Our migration guide walks you through it step by step.
Whether you’re researching or ready to move, we can help
Try a Self-Guided Demo
Reduce Check Costs
The cost of processing checks is almost always higher than finance teams realize, and it’s the clearest argument for vendor payment automation.
When you account for the full cycle: staff time to cut and approve checks, postage and supply costs, manual reconciliation, returned check handling, and re-issuance, industry estimates put the true cost of a single check at $4 to $20 per transaction, compared to less than $1 for ACH.
At scale, that gap is significant. An organization issuing 10,000 checks a year at an average fully-loaded cost of $10 is spending $100,000 annually on a payment method that is slower, less secure, and harder to reconcile than the alternative.
The cost of processing checks also extends beyond the transaction itself. Check fraud losses, stop-payment fees, and the staff hours spent investigating payment exceptions all belong in the calculation, and they rarely show up in the initial estimate.
Move to ACH Safely
Migrating vendors to ACH is one of the highest-ROI initiatives available to a modern AP team, and it’s a natural extension of vendor payment automation. It’s also one of the most operationally complex moves you can make, and when it’s done carelessly, it creates exactly the kind of fraud exposure it was meant to eliminate.
The risks of switching to ACH aren’t theoretical. Collecting banking details through insecure channels, relying on vendor self-reporting without authentication, and failing to validate account ownership before the first payment are among the most common ways ACH migrations go wrong. A fraudster only needs one opportunity to redirect a payment to an account they control.
Done right, an ACH migration means:
- Collecting banking details through a secure, authenticated means — not email or paper forms
- Authenticating account ownership at the point of entry, before any payment is issued
- Transferring fraud liability through a defensible authentication process
- Maintaining a complete audit trail for every vendor banking change throughout the migration
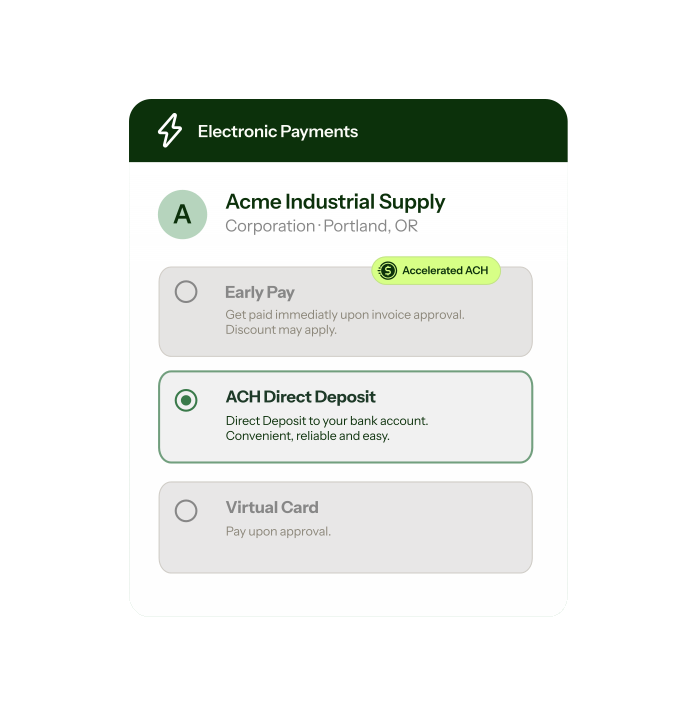
With PaymentWorks, vendors onboard through an authenticated platform and workflow — so the banking details entering your ERP are clean from day one, and the fraud risk that typically accompanies a migration stays off your books.
Ready to Learn More About Vendor Payment Automation?
We’ll walk you through how much your current process is costing you.
Speak With a Specialist